Overview of Arizona Excess Sale Proceeds

What is the Arizona foreclosure process?
When a borrower doesn’t perform their financial obligations, a lender may legally seize and sell a home or other property. This method is called foreclosure. There are various types of foreclosures in Arizona.
- The trustee’s sale procedure is the most used in Arizona. When the lender decides to foreclose on the borrower’s property, there are laws governing the process. Normally the trustee’s sale, in comparison to other processes, is cheaper and quicker (at least 90 days). In this method, there is no court involvement.
- The second process is a judicial foreclosure. This is a court procedure. Therefore, it is more expensive and takes longer. The advantage for the lender is that a deficiency action could be brought against the borrower or guarantor. The homeowners’ association (“HOA”), or those who purchased back taxes may also use this court process.
- The sheriff’s sale comes after the judicial foreclosure. As was already mentioned, the process begins in court. The task of selling the property is then given to the sheriff. Lenders, HOAs, and investors in back taxes normally use this.
The following will discuss a few of the fundamental of Arizona trustee’s sale, foreclosure and tax liens
What choices does a lender have in the event
that the mortgage is not paid?
A foreclosure or trustee’s sale is usually recorded by the lender. A procedure, such as a trustee sale or foreclosure, is governed by the laws of the state where your Arizona trustee sales real property is located. Arizona permits a lender to choose either course of action. You should see a local lawyer who is experienced in this field of law because all states do not have the same laws. Because each person’s situation is different and the legal and tax advice you will receive will vary greatly, do not rely on the internet for correct information.
What is a Judicial foreclosure, and how does it work?
A court-filed legal action known as a judicial foreclosure (this is a court process). The real estate’s owner is served with the notice and given the chance to respond. In the end, the court will issue a judgment, typically in the lender’s favor. The law in the state where the property is located determines what occurs next. The next step in Arizona is a Sheriff’s sale.
What is a trustee’s sale, and how does it work?
A trustee is hired by a lender to collect the money they’ve invested in the property by selling it at a public auction.
If other people bid at the auction, the lender is compensated. If no one bids on the property, the lender becomes the new owner.
What happens once a trustee’s sale or foreclosure is finished? Most likely there will be an eviction.
After a lender completes the trustee’s sale or foreclosure There will be a new owner of the property. Most likely, the new owner will want the previous owner or tenant to vacate the real estate, therefore they will file a forcible entry and detainer action (again, under Arizona law), also known as a FED.
The tenant/occupant is served with a written notice to vacate the premises. The length of the notice to vacate is determined by the type of occupancy, type of lease – commercial or residential, and whether the property is occupied by a renter or a foreclosed owner. Unless the contract specifies otherwise, this period is usually 5 or 7 days. If the tenant/occupant refuses to leave after the 5-7 days have passed, a complaint for forceful detainer action might be initiated. A notice of hearing will be delivered to the property’s occupant. In the end, the new owner will get an eviction order requiring the resident (often the previous owner or tenant) to vacate by a certain time. If the tenant, or old owner, does not leave then the sheriff will forcibly evict the occupant.
If the property is residential (ARS 33-1377) or non-residential (ARS 33-361), the laws regulating forcible entry and detainer actions are different (ARS 33-361).
What happened to any money that was left over after my house was sold at a trustee’s sale or during a foreclosure?
The money in question is known as “excess sale proceeds“. The application process for the funding is set by law. NEVER give up the opportunity to pursue out those monies. Instead, consult an expert lawyer instead so that you are aware of your rights.

Our homes are typically both our most expensive investment and most treasured property.
As a creditor’s attorney many years ago, I conducted thousands of trustee sales in Arizona. Because I wanted to help people keep their homes and prevent them from being lost, I left that industry.
The homeowner should always seek legal and tax advice before moving forward with a trustee’s sale (foreclosure), short sale, or deed in lieu of foreclosure. After the process is finished, significant mistakes cannot be fixed.

As your circumstances change, you might need to learn about your options for dealing with a home that is suddenly a burden.
The rights and obligations of the landowner and the landowner’s creditors are typically defined by the laws of the state where the land is located (except federal lands). The laws that set the rules of the land differ in each state. As soon as your financial situation becomes troubling, see a knowledgeable attorney who specializes in bankruptcy and foreclosure to learn about your choices. You could be pleasantly surprised by your options.

Am I Eligible to File Bankruptcy in Arizona?
Chapter 7 Qualifications
The means test is the major qualification for Chapter 7 debtors. If your annual household income is less than the national average, you may be eligible for this type of bankruptcy. This figure is updated every few months.
If you do not qualify for Chapter 7, other options, such as Chapter 13 bankruptcy are usually available.
Chapter 13 Qualifications
In Chapter 13 cases have limits on the amount and type of debts. There is also a minimum income and expense requirement. Debtors in Chapter 13 must have enough disposable income to make a monthly plan payment.
Helpful Insight
The right to file Bankruptcy bankruptcy is Protected by the United States Constitutional.
As early as 1789, Congress was authorized by the US Constitution’s Art. 1, Section 8, Clause 4 to enact bankruptcy laws to assist all citizens in obtaining a fresh start. The first bankruptcy law was enacted in 1800. Clearly, this option has been viewed as an important tool for protecting our citizens. As a result, you should never feel obligated to apologize to me or anyone else for exercising your constitutional rights.
Arizona Bankruptcy Law
When you file for bankruptcy, an automatic stay is triggered, which immediately stops things like:
- Repossession
- Wage garnishment
- Foreclosure
- Lien placement
- Creditor harassment
The protected repayment period in a Chapter 13 and immediate debt discharge in a Chapter 7 are two other features of bankruptcy law. If you file for Chapter 13, you will have three to five years to catch up on mortgage payments and other delinquent secured debts. If your income is above the median income you will most likely have a five year plan (there are exceptions). Most credit card, medical bill, and other unsecured debt is eliminated in a few months under Chapter 7. But any non-exempt property can be seized and sold to pay your creditors. The result is different in a Chapter 13.

Confused? Of course! That is why it is very important to have an experienced Arizona bankruptcy attorney on your side and helping you with the options.
Bankruptcy in Arizona is a complex interaction of multiple laws that should not be attempted without competent legal counsel.
Do not hire inexperienced attorneys who are unfamiliar with bankruptcy law. I say this not to scare you, but because I’ve seen good people make bad and costly decisions without realizing it.
What are the terms “Pre-Petition Assets” and “Pre-Petition Debts”? What are Assets and Debts after filing the bankruptcy in Arizona?
Pre-petition assets are assets that you owned prior to filing for bankruptcy. Some of these assets may be used to settle pre-petition debts, or payments owed prior to filing for bankruptcy. In a chapter 7, any assets you obtain after filing for bankruptcy in Arizona are usually considered post-petition assets, and most of your pre-petition creditors cannot seize them. Similarly, any liabilities you incur after filing for bankruptcy, referred to as post-petition liabilities, are not discharged in a bankruptcy proceeding. But note that this may differ slightly in a chapter 13 case.
Diane helped me retain my dignity
"Diane helped me retain my dignity ." S & A *Diane helped me retain my dignity during a very uncomfortable time. I am very grateful.
She was more interested in my welfare than in charging a fee
She was more interested in my welfare than in charging a fee. L.B. I cannot tell you how grateful I am that Diane Drain took my call. I was desperate and she made me feel that I could sleep through the nite. She explained all my options [...]
She knows the ins and outs
"She knows the ins and outs" M.D. I’ve been in the legal field for over 25 years (as a legal secretary and paralegal) and Diane is a top notch attorney. She knows the ins and outs of this area of law and does a really great job of explaining [...]
Just wanted to share our story so you can share with others that come in
“Just wanted to share our story so you can share with others that come in” K.T. Diane I just wanted to give you an update on us. We filed bk with you representing us about 7 years ago now. Just wanted you to know we are doing [...]
Diane and Jay Answered All Our Questions
“They answered all our questions patiently and thoroughly explained the legal processes and what we could expect so there were no surprises. .” T.D and R.I. Diane and Jay are an absolutely phenomenal professional team. Bankruptcy is not an easy undertaking and there [...]
Diane and Jay are a great team
“Amazing experience” L.A. Diane and Jay are a great team. Diane took the time to explain every step of the way and provide me with so much education regarding my bankruptcy. The material I obtain was and is very helpful to have a stable life. Thank you [...]
Thank you so much for your help
"Thank you so much for your help." S. Thank you so much for your help. I feel very good about my decision and I’m so very glad I chose you to represent me.
Diane Helped Me Understand the Process
“She helped me understand why and how certain steps were necessary...” N.G.. I greatly appreciated Diane's thoroughness and ability to explain the process. She helped me understand why and how certain steps were necessary which reassured me that this was the right decision to make and that [...]
Wonderful attorney
“Wonderful attorney” Anon She helped us with our bk 7 years ago and not only did she do a wonderful job representing us she taught us a few things about money! We are doing great now with great credit scores, a new home and cars all within [...]
Diane Was Fabulous During Our Bankruptcy
“Her assurance that there was nothing to be ashamed of, gave us the incentive to proceed.” S.R. Diane was fabulous during our bankruptcy, guiding us every step of the way. After medical bills got us behind, we didn't know where to turn and felt uncomfortable filing. Her [...]
ROCKSTARS Diane and Jay!!! I am so happy
“ROCKSTARS Diane and Jay!!! I am so happy ” P.C. ROCKSTARS Diane and Jay!!! I am so happy to work with you again. Within a few months, you got me the BEST results. You did exactly what you said you would do. You went above and beyond [...]
Diane is great
"Diane is great" G.S. Diane is great. After looking around for an attorney, I couldn’t be anymore happier with my decision of going with her. She answered all of my questions and took her time with me. Very motherly and straight forward. It’s very hard to find an [...]
Diane and Jay were very patient with us
"Diane and Jay were very patient with us" N & J Diane and Jay were very patient with us in explaining every important detail involved in our case which helped ease the anxiety that sometimes came when we felt unsure about certain questions, Thank you. [...]
You gave us great guidance
“You gave us great guidance.” J.B. Thank you !!! Diane and Jay for all your help. I would highly recommend your services. You were very caring and helpful during the whole process. You gave us great guidance through a very stressful time. We appreciate it. [...]
Diane is very concerned for your well-being
“My anxiety faded away with each conversation we had ” R.L. If you are considering a bankruptcy, there is no other person in the state of Arizona to talk with other than Diane Drain. She is very concerned for your well-being. Her knowledge and expertise allowed me [...]
ow I can finally breathe easy and deep again
"I can finally breathe easy and deep again." J. Thank you so so much for all your help and understanding. Especially in the beginning when I had so many questions and you were so very patient with me. I felt that you were very upfront about everything, letting [...]
We were extremely pleased
"We were extremely pleased!" Anonymous We were extremely pleased with the quality and level of support you and Jay provided. We had shopped around a bit before contacting you and once we did the comparison with other attorneys and bankruptcy “mills” was extremely and significantly positive. [...]
Highly recommend Diane and Jay
Highly recommend Diane and Jay. C.T. Diane and Jay were not only very knowledgeable and patient, but they took time to educate me and point me to the resources I needed. Diane and Jay walked me through every step and worked with me through any confusion or [...]
The Human Dilemma — Being Bad Is Easier Than Being Good
Doing the wrong thing is often easier than doing the right thing. But perhaps that is exactly why honesty, kindness, courage, and responsibility have value. Character is often revealed when the easier choice is available, but we choose the better one.
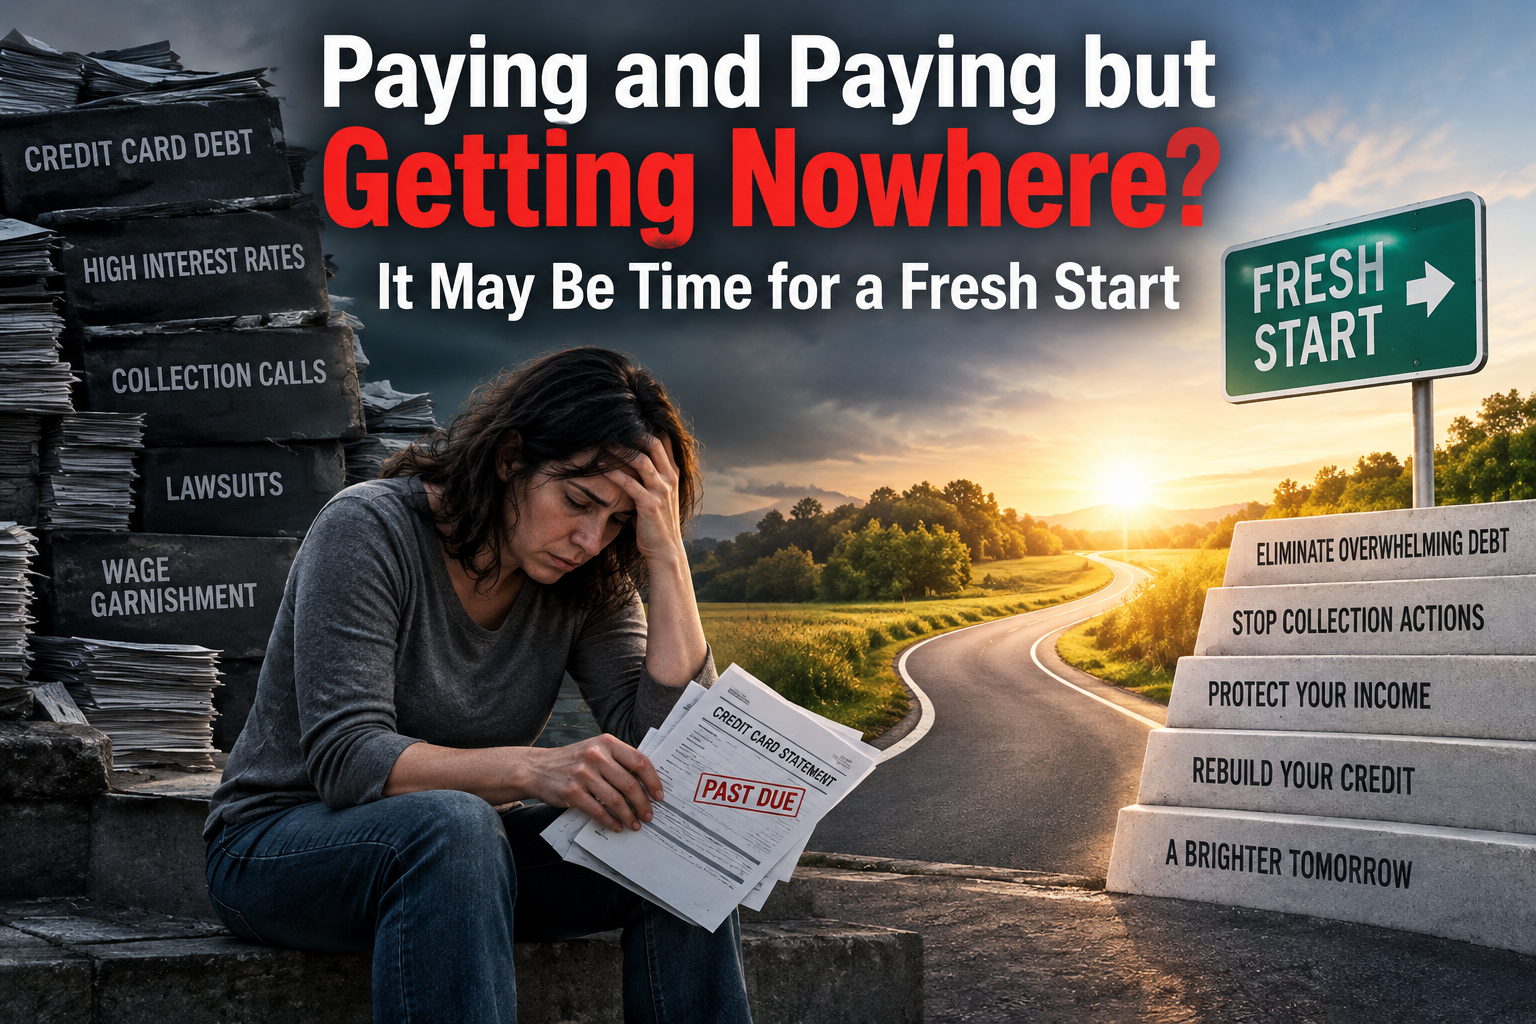
Paying and Paying but Getting Nowhere? It May Be Time for a Fresh Start
Paying debt every month but getting nowhere can cost you years of income and thousands of dollars in interest. Before signing up with a debt management or debt settlement company, understand what debts are covered, what fees you may pay, whether creditors can still sue or garnish wages, and whether forgiven debt could create tax problems. For some people, bankruptcy may provide a faster, more complete fresh start and a chance to rebuild.
Debt Settlement Can Wreck Your Credit — Even If You’re Paying on Time
Thinking About Debt Settlement? Read This Before You Stop Paying Debt settlement may sound like an easier and safer choice than bankruptcy. You have probably [...]
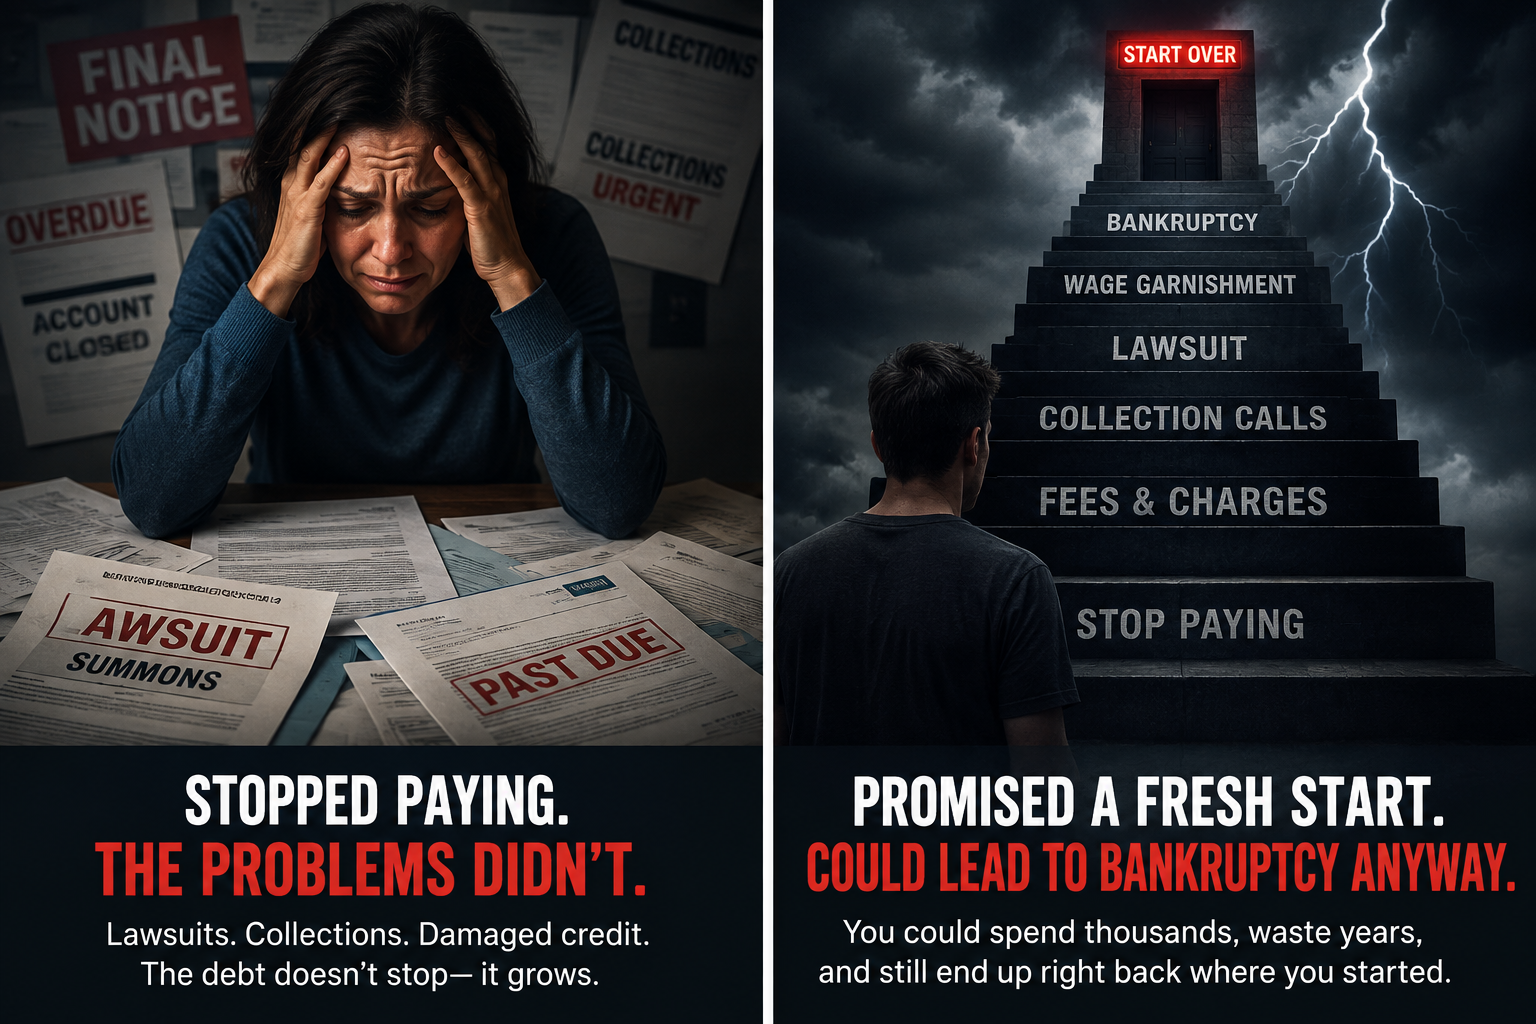
The Debt Settlement Trap: What Happens When the Promises Don’t Work?
Debt-settlement companies promise to reduce what you owe, but creditors do not have to settle. Learn what federal regulators say about growing balances, lawsuits, fees, taxes and other debt-settlement risks before you stop paying your creditors.