The Automatic Stay v. the Bankruptcy Discharge
 The Fair Credit Reporting Act “FCRA” and the Bankruptcy Code deal with debt differently and this difference can become confusing for everyone, including experienced bankruptcy attorneys. For instance, the legal status of a debt changes as a bankruptcy moves to conclusion. At the beginning of a bankruptcy the automatic stay stops most creditors seizing assets from the bankruptcy estate’s assets without an order from the Bankruptcy Court. But the debt is still the same as before the bankruptcy was filed. If the case is dismissed the creditor has all the same rights as before the bankruptcy was filed. Reporting the debt to the credit bureaus has raised lots of issues in bankruptcy. Many courts have found there is no liability under the FCRA to report a debt as being in default, at least until the case is discharged.
An order discharging the debt alters the legal nature of the debt and prohibits collection efforts.
 Once the order of discharge is entered it “operates as an injunction against the commencement or continuation of an action … to collect, recover or offset any such debt as a personal liability of the debtor.” Therefore, a discharge order (unlike the automatic stay) alters the legal nature of the debt. Many courts have interpreted the FCRA to require credit reporting agencies “CRA” and furnishers to adjust credit reports after an order of discharge, otherwise be liable under the FCRA (not all courts follow this line of thought).
Reorganizations
Plans of reorganization are a key component of Chapter 11 and 13 cases. In order for a reorganization to be successful a plan must be confirmed and completed. The challenge for the courts is to determine how the debts should be reported on a credit report before completion of the plan. The order confirming the plan binds the debtor and creditors to the plan’s provisions, and controls any contracts that existed before the bankruptcy was filed, including the amount to be paid and lien priority. Once the plan is confirmed the United States Supreme Court determined that creditors may not relitigate their treatment under the plan (basically they already had their shot at the apple). Although confirmation binds the parties to the plan’s terms, it does so only as long as the case is active and is subsequently discharged.
If a case is dismissed the debts return to the same position as before the bankruptcy was filed, offset by any monies the creditors received during the case.
 Given that the bankruptcy is not completed until discharge this raises the issue of whether a credit report can be determined to be inaccurate or misleading if it discloses the pre-petition debt after the bankruptcy court confirms a plan reducing the amount to be paid on the claim, or if it must report the amount established by the confirmed plan (not yet discharged). You can see the quandary.

Diane is a well respected Arizona bankruptcy and foreclosure attorney. As a retired law professor, she believes in offering everyone, not just her clients, advice about bankruptcy and Arizona foreclosure laws. Diane is also a mentor to hundreds of Arizona attorneys.
*Important Note from Diane: Everything on this web site is offered for educational purposes only and not intended to provide legal advice, nor create an attorney client relationship between you, me, or the author of any article. Information in this web site should not be used as a substitute for competent legal advice from an attorney familiar with your personal circumstances and licensed to practice law in your state. Make sure to check out their reviews.*



In Case You Missed It
Published On: September 13, 2026
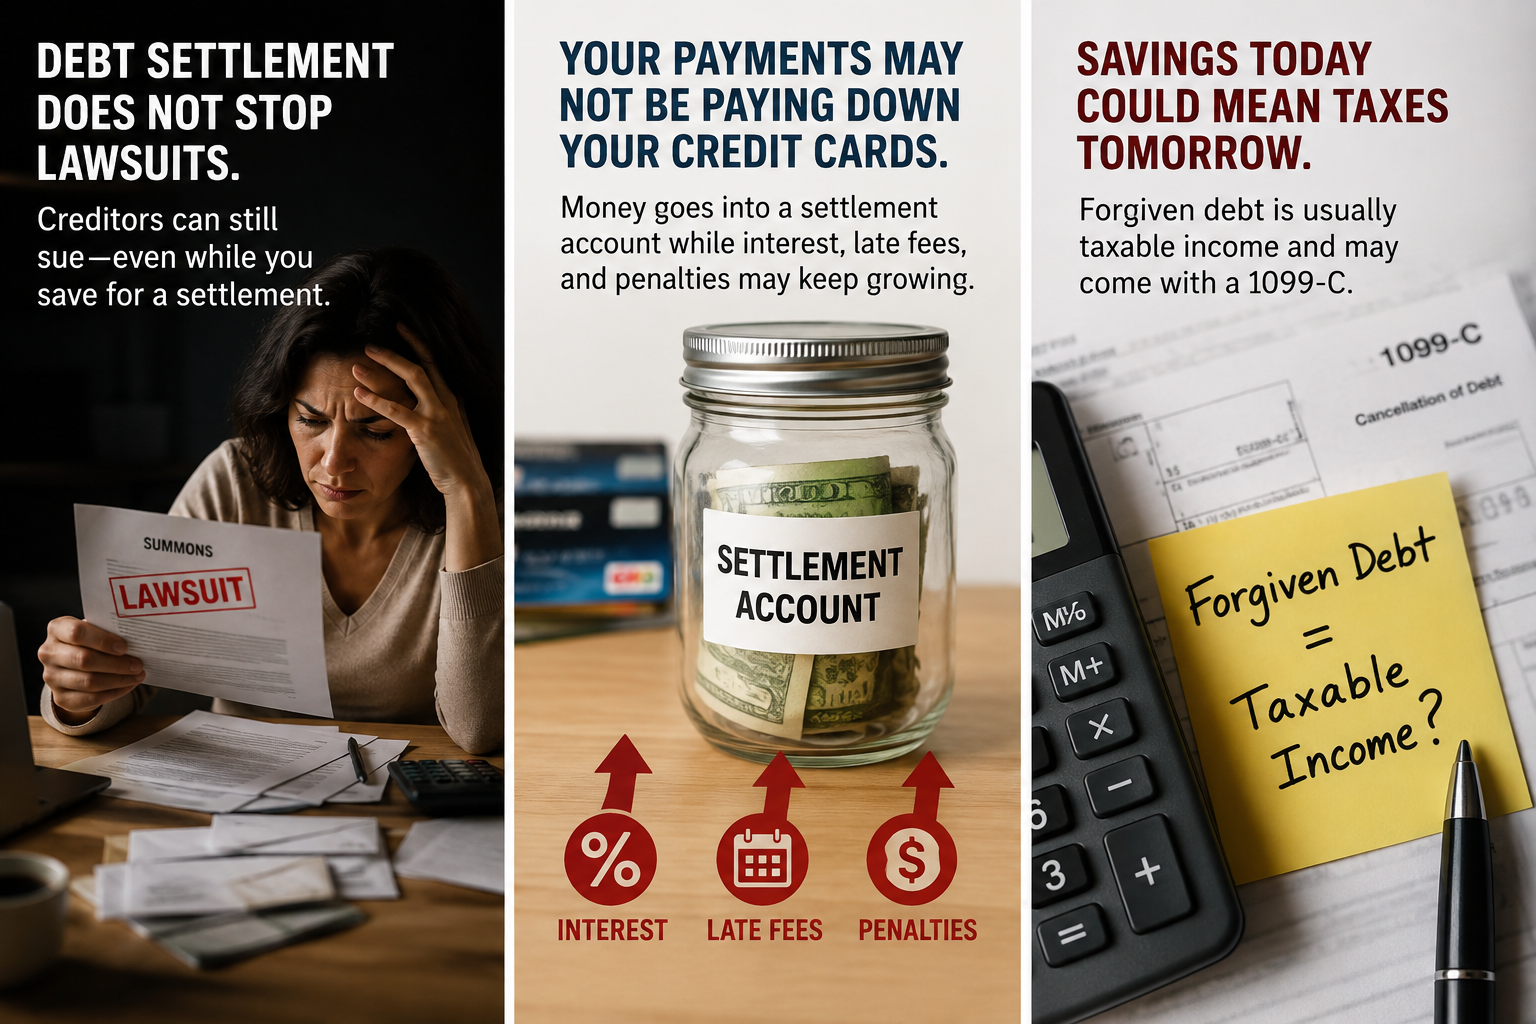
Paying debt every month but getting nowhere can cost you years of income and thousands of dollars in interest. Before signing up with a debt management or debt settlement company, understand what debts are covered, what fees you may pay, whether creditors can still sue or garnish wages, and whether forgiven debt could create tax problems. For some people, bankruptcy may provide a faster, more complete fresh start and a chance to rebuild.
Published On: September 13, 2026
Thinking About Debt Settlement? Read This Before You Stop Paying Debt settlement may sound like an easier and safer choice than bankruptcy. You have probably seen the ads: “Pay only a fraction of what you [...]
Published On: August 9, 2026
Debt-settlement companies promise to reduce what you owe, but creditors do not have to settle. Learn what federal regulators say about growing balances, lawsuits, fees, taxes and other debt-settlement risks before you stop paying your creditors.
Published On: August 8, 2026
Debt settlement companies promise relief from overwhelming debt, but creditors do not have to settle and lawsuits can continue. Learn about the hidden fees, growing balances, tax consequences, and alternatives before signing a contract.