How long after bankruptcy do I have to wait before buying a home?
So many questions about bankruptcy.
Anyone who either filed for bankruptcy or is considering it has asked “how long before I can buy a new home”? Attached is a spreadsheet which purports to detail the answer to this question. But, beware – each of the lenders can and do change their minds every few months. Also, there is nothing written in stone that says a lender must follow these guidelines. They are only suggestions.
Here is the link (dated April, 2018)
The more important question should be “is bankruptcy a good way to get a fresh start for myself and my family?”
It is very important to focus on what you and your family need today, with a plan for the short term future, such as paying off the car.
Buying a home will come later. Many of my clients report that they were able to purchase a new home within two years after filing the bankruptcy, but this really depended on their post-bankruptcy payment history. It also depends on whether they have the financial ability to pay for a home (which costs far more than the monthly payment). Too often I see my clients fail in their goal to buy a home because they fall back into the trap of living off credit cards (sometimes that is a very hard habit to break).
MUSINGS BY DIANE:
I offer each of my clients a book and articles on how to rebuild their credit, with the hopes that some of the ideas will be helpful. I also warn them about buying into any fast and easy “credit repair”. THEY ARE ALL SCAMS!! Don’t throw away your hard earned money and hopes for a better future on these frauds.

Diane is a well respected Arizona bankruptcy and foreclosure attorney. As a retired law professor, she believes in offering everyone, not just her clients, advice about bankruptcy and Arizona foreclosure laws. Diane is also a mentor to hundreds of Arizona attorneys.
*Important Note from Diane: Everything on this web site is offered for educational purposes only and not intended to provide legal advice, nor create an attorney client relationship between you, me, or the author of any article. Information in this web site should not be used as a substitute for competent legal advice from an attorney familiar with your personal circumstances and licensed to practice law in your state. Make sure to check out their reviews.*



In Case You Missed It
Published On: September 13, 2026
Paying debt every month but getting nowhere can cost you years of income and thousands of dollars in interest. Before signing up with a debt management or debt settlement company, understand what debts are covered, what fees you may pay, whether creditors can still sue or garnish wages, and whether forgiven debt could create tax problems. For some people, bankruptcy may provide a faster, more complete fresh start and a chance to rebuild.
Published On: September 13, 2026
Thinking About Debt Settlement? Read This Before You Stop Paying Debt settlement may sound like an easier and safer choice than bankruptcy. You have probably seen the ads: “Pay only a fraction of what you [...]
Published On: August 9, 2026
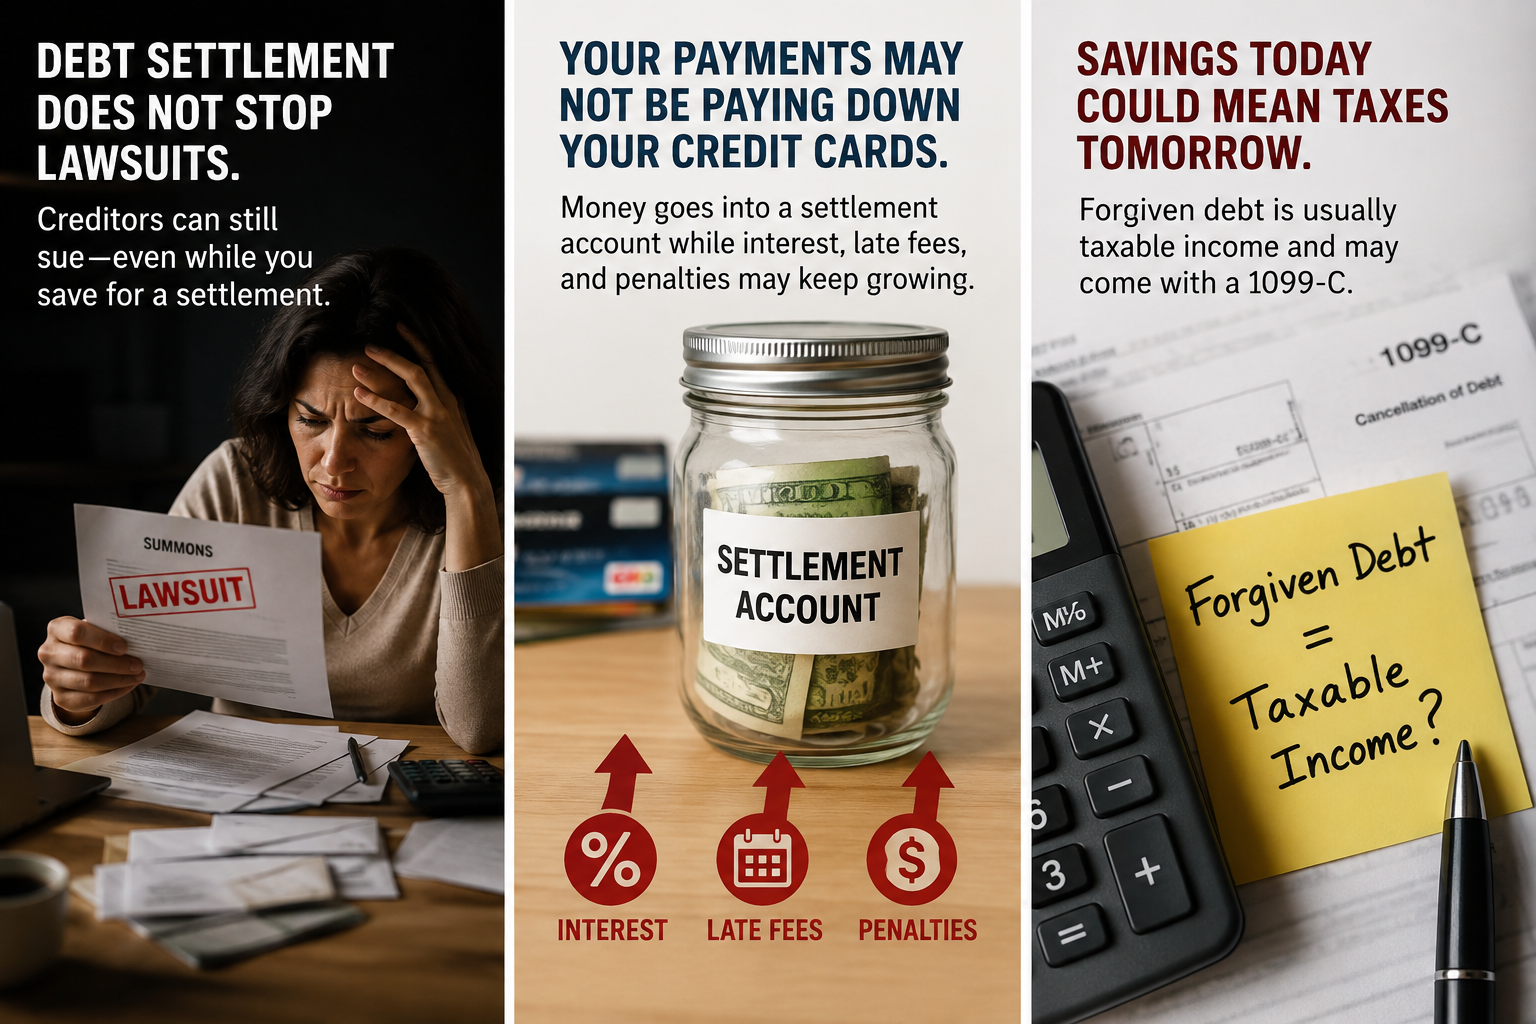
Debt-settlement companies promise to reduce what you owe, but creditors do not have to settle. Learn what federal regulators say about growing balances, lawsuits, fees, taxes and other debt-settlement risks before you stop paying your creditors.
Published On: August 8, 2026
Debt settlement companies promise relief from overwhelming debt, but creditors do not have to settle and lawsuits can continue. Learn about the hidden fees, growing balances, tax consequences, and alternatives before signing a contract.