What is a Judgment Debtor’s Examination
The following applies to Arizona lawsuits and collection rights.
When a creditor sues and obtains a judgment there are several options available in order to collect on the judgment. The one that is the most scary for the consumer is the “judgment debtor’s examination”.
The creditor may hire an investigator to do a “skip trace”, probably before the debtor’s exam, in order to determine what assets the judgment debtor owns. Once the creditor has the judgment they can legally obtain additional information under federal laws (FCRA, FDCPA, etc.) than before they had the judgment.
 What if the judgment debtor (the person sued) refuses to appear at the debtor’s exam?
If the judgment debtor does not appear for a properly noticed and served debtor’s exam, the judgment creditor can ask the issuing judge/commissioner for a civil arrest warrant. To issue such a warrant, the judge/commissioner will require the judgment debtor’s name, address, date of birth, and if available, a physical description and driver’s license number. The important point is never ignore a subpoena, unless you are in bankruptcy or your attorney explains why you do not need to appear.
What does the creditor do at a judgment debtor’s exam?
 The creditor will ask the judgment debtor to produce bank statements, tax returns, car titles, payroll information, list of all debts and expenses, lease or deed of trust, location of all assets, how bills are paid (by check, cash or money in someone else’s account)
In addition to asking the judgment debtor for this information the judgment creditor can subpoena bank and brokerage account statements, garnish wages and require a sheriff to sell any property that is not exempt in order to satisfy the judgment.
Bankruptcy will stop the debtor’s examination.
Normally, unless this is a criminal charge, the threat of a debtor’s examination and seizure of assets ceases when a bankruptcy is filed. But beware, if the debtor has committed fraud, caused damage by DUI and other exceptions, the bankruptcy may not stop or discharge those actions or debts.

Diane is a well respected Arizona bankruptcy and foreclosure attorney. As a retired law professor, she believes in offering everyone, not just her clients, advice about bankruptcy and Arizona foreclosure laws. Diane is also a mentor to hundreds of Arizona attorneys.
*Important Note from Diane: Everything on this web site is offered for educational purposes only and not intended to provide legal advice, nor create an attorney client relationship between you, me, or the author of any article. Information in this web site should not be used as a substitute for competent legal advice from an attorney familiar with your personal circumstances and licensed to practice law in your state. Make sure to check out their reviews.*



In Case You Missed It
Published On: September 13, 2026
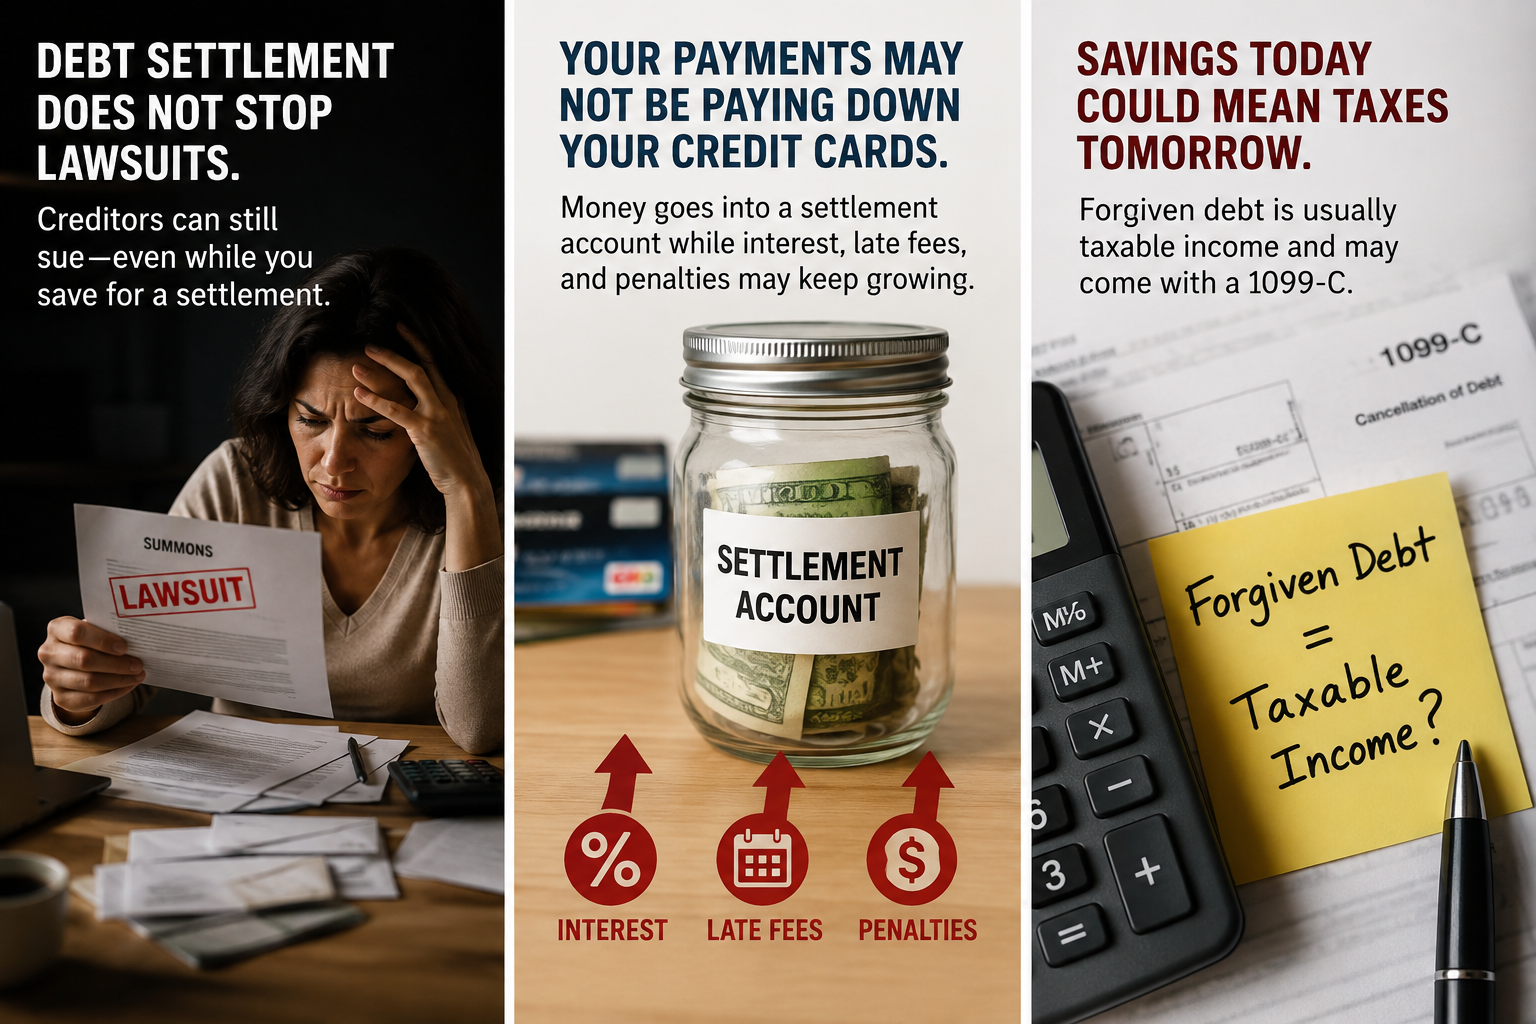
Paying debt every month but getting nowhere can cost you years of income and thousands of dollars in interest. Before signing up with a debt management or debt settlement company, understand what debts are covered, what fees you may pay, whether creditors can still sue or garnish wages, and whether forgiven debt could create tax problems. For some people, bankruptcy may provide a faster, more complete fresh start and a chance to rebuild.
Published On: September 13, 2026
Thinking About Debt Settlement? Read This Before You Stop Paying Debt settlement may sound like an easier and safer choice than bankruptcy. You have probably seen the ads: “Pay only a fraction of what you [...]
Published On: August 9, 2026
Debt-settlement companies promise to reduce what you owe, but creditors do not have to settle. Learn what federal regulators say about growing balances, lawsuits, fees, taxes and other debt-settlement risks before you stop paying your creditors.
Published On: August 8, 2026
Debt settlement companies promise relief from overwhelming debt, but creditors do not have to settle and lawsuits can continue. Learn about the hidden fees, growing balances, tax consequences, and alternatives before signing a contract.