Lenders use abusive or unfair practices to trap low income into a never-ending cycle of debt. Learn to spot the scams:
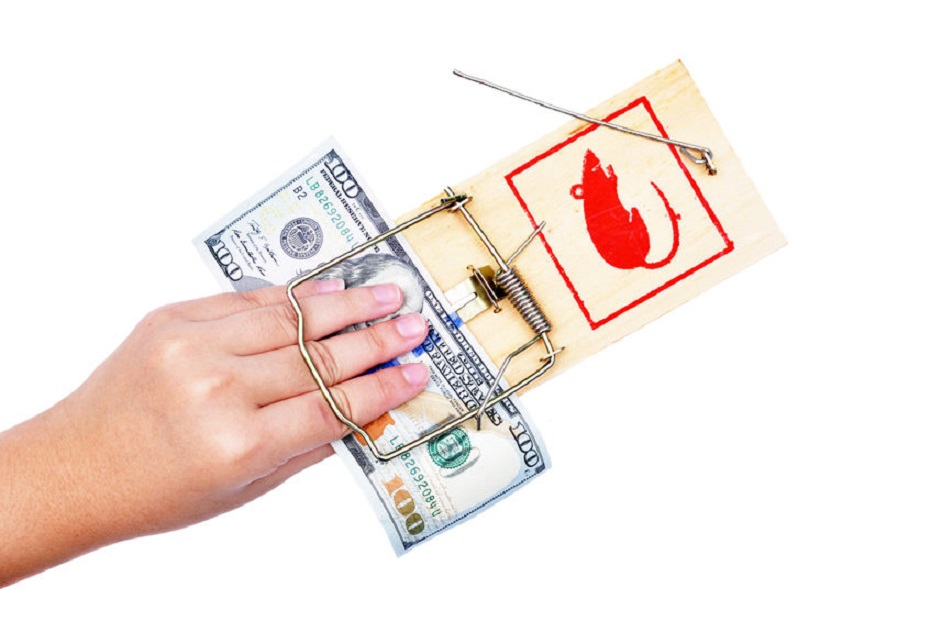 The goal of a predatory loan (such as payday loans) is to trap the borrower in a nightmare of never-ending debt. The lenders know that no one is watching or, in some cases, cares that the poor are preyed upon by these unscrupulous lenders. Those lenders hope that their schemes to keep the poor paying outrageous interest rates, which forces them to take out more payday loans. There are a few states taking action – see State Payday Loan Reform from Pew Charitable Trusts, a nonprofit public interest group.
The following are highlights from an article by Annie Millerbernd of Nerd Wallet, November 19, 2019
Five signs of a predatory loan:
- No Credit Check Ads. The lenders make it as easy a possible for the unwary borrower to get trapped in the never-ending loan cycle.
- Focus on Monthly Payments. Like a magician trying to distract you – the lender advertises low monthly payments but hides the length of the loan or very, very high-interest rates.
- Sky-High Rates. A bad lender is one that hides the interest rate on its website or advertisement. They hope to distract you by flashing signs and soothing language offering to solve all your problems (I call this the drug dealer’s promise). There are reports of interest rates 300% to 700%. For instance, if you borrow $10, you have to repay $50.
- Excessively Long or Short Repayment Periods. Many predatory loans result in the borrower paying more than they originally borrowed (sometimes as much at 5-7 times more).
- All-in-one Payment Requirements. According to Alex Horowitz, a senior research office with Pew Charitable Trusts, “the average payday loan takes 36% of a borrower’s paycheck.” If the borrower cannot make the payment (few ever can), they take another loan to pay the first loan – the cycle goes on for years until the borrower finally sells their only vehicle to pay the debt or files bankruptcy.
 MUSINGS FROM DIANE:
 Desperate people do desperate things. Some rob to feed their family. Others gamble their entire paycheck with the hopes of winning enough to pay the mortgage. What most don’t do is ask for help or seek informed advice from those who care.
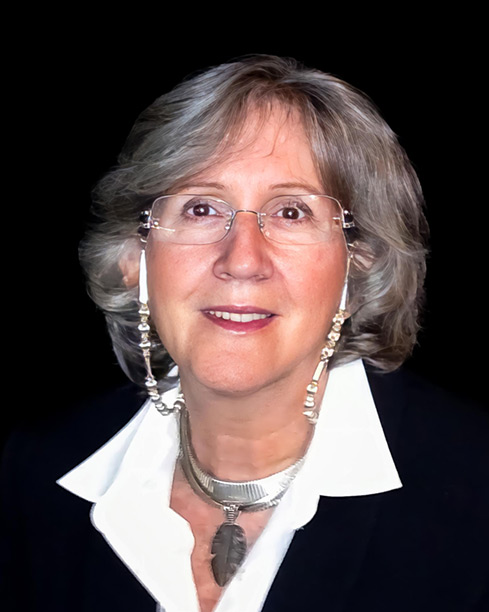

Diane is a well respected Arizona bankruptcy and foreclosure attorney. As a retired law professor, she believes in offering everyone, not just her clients, advice about bankruptcy and Arizona foreclosure laws. Diane is also a mentor to hundreds of Arizona attorneys.
*Important Note from Diane: Everything on this web site is offered for educational purposes only and not intended to provide legal advice, nor create an attorney client relationship between you, me, or the author of any article. Information in this web site should not be used as a substitute for competent legal advice from an attorney familiar with your personal circumstances and licensed to practice law in your state. Make sure to check out their reviews.*



In Case You Missed It
Published On: September 13, 2026
Paying debt every month but getting nowhere can cost you years of income and thousands of dollars in interest. Before signing up with a debt management or debt settlement company, understand what debts are covered, what fees you may pay, whether creditors can still sue or garnish wages, and whether forgiven debt could create tax problems. For some people, bankruptcy may provide a faster, more complete fresh start and a chance to rebuild.
Published On: September 13, 2026
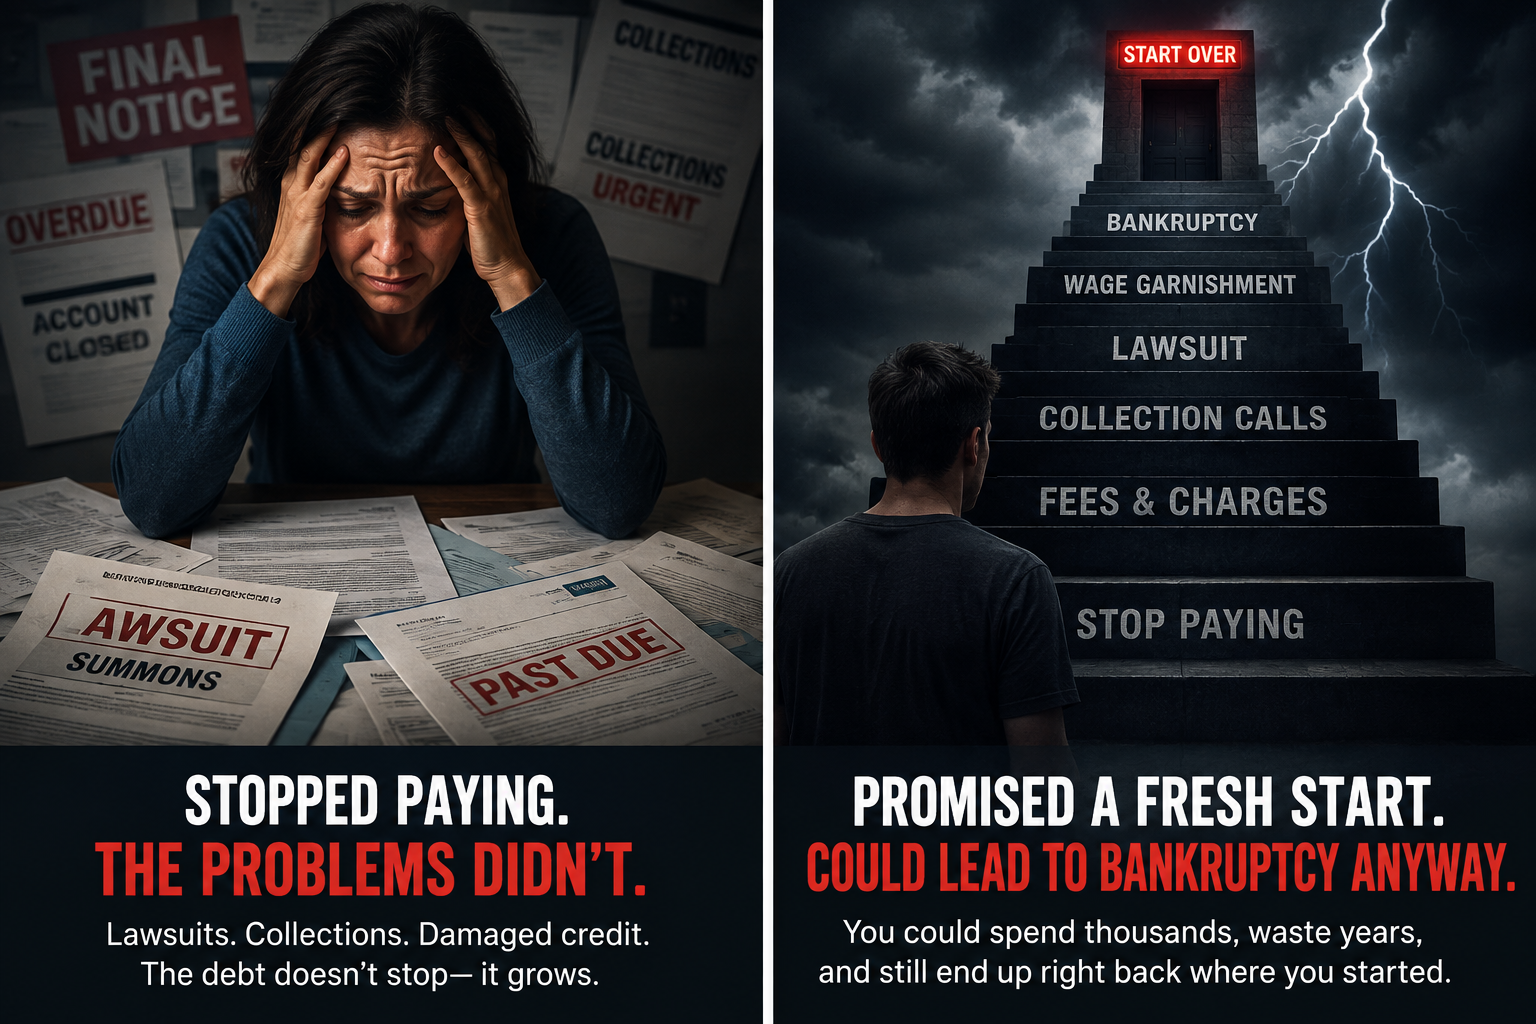
Thinking About Debt Settlement? Read This Before You Stop Paying Debt settlement may sound like an easier and safer choice than bankruptcy. You have probably seen the ads: “Pay only a fraction of what you [...]
Published On: August 9, 2026
Debt-settlement companies promise to reduce what you owe, but creditors do not have to settle. Learn what federal regulators say about growing balances, lawsuits, fees, taxes and other debt-settlement risks before you stop paying your creditors.
Published On: August 8, 2026
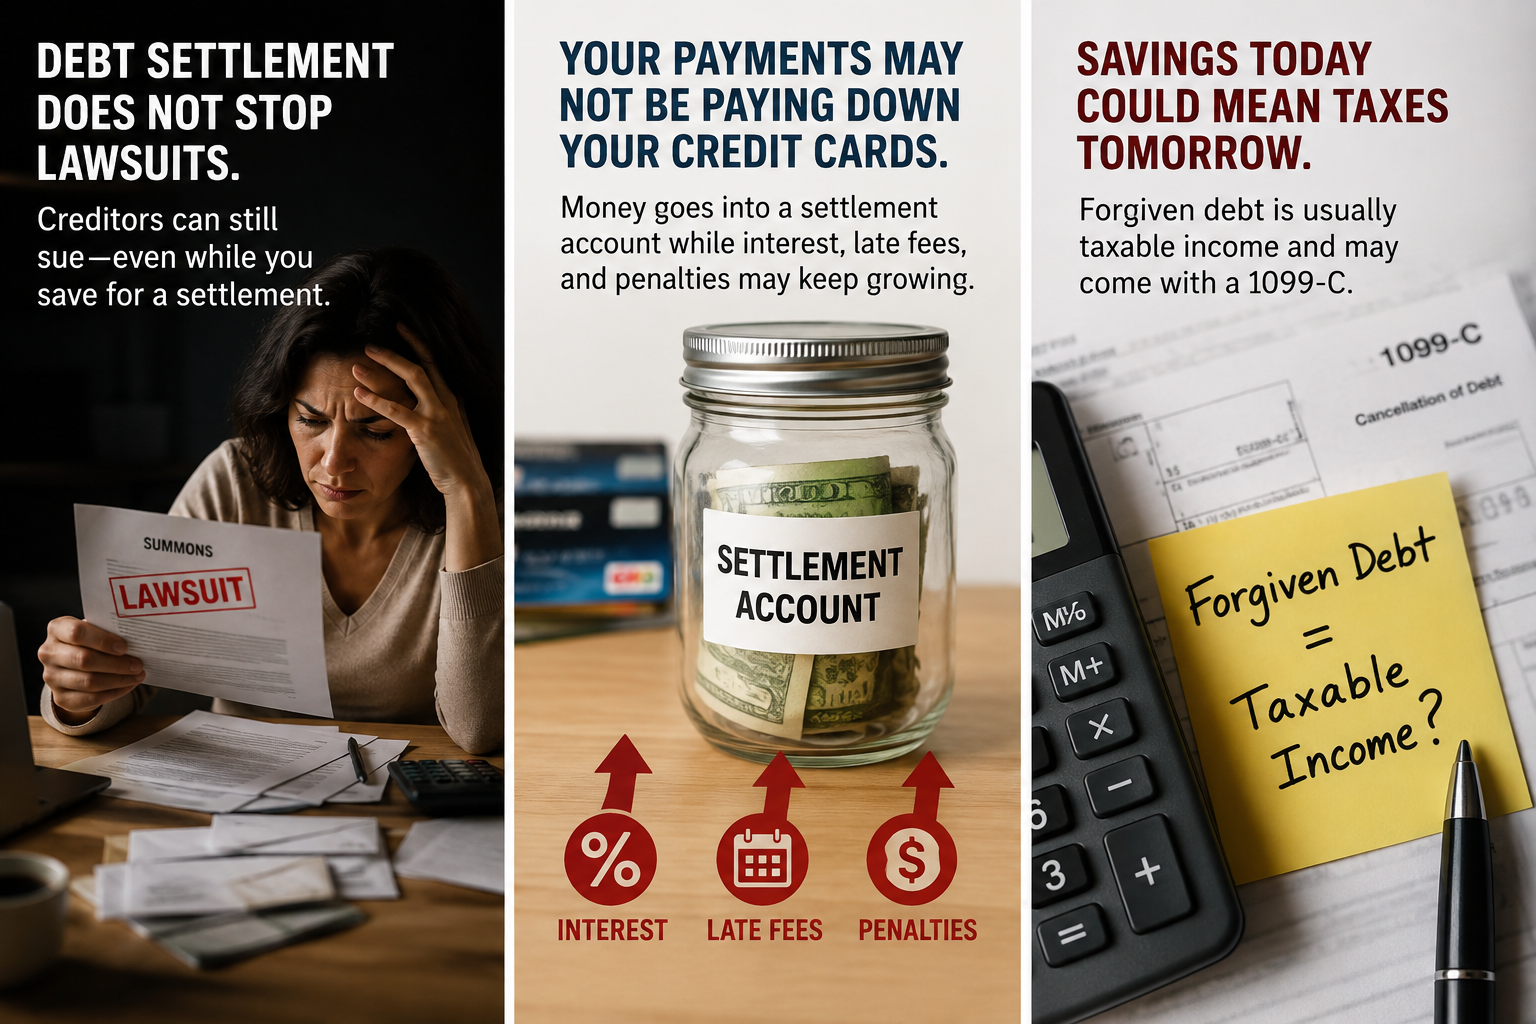
Debt settlement companies promise relief from overwhelming debt, but creditors do not have to settle and lawsuits can continue. Learn about the hidden fees, growing balances, tax consequences, and alternatives before signing a contract.