Subprime Vehicle Loans are Skyrocketing
Subprime vehicle loans – according to an article in Automotive News and Bloomberg “about a third of the risky car loans that are bundled into bonds are considered “deep subprime,” a level that has surged since 2010 and is translating to higher delinquencies on the loans, according to Morgan Stanley.”
 Automotive financing is following the wise (that is intended to be sarcastic) decisions made in the mortgage lending market. Surprise – Morgan Stanley’s Vishwanath Tirupattur, James Egan and Jeen Ng said in a report dated March 24 that “consumers are falling behind on most subprime car loans, but deep subprime borrowers have deteriorated fastest.” The subprime loans are sold on the high-risk lending market in a method referred to as “securitization”. Which means loans that are high risk are bundled together and sold to investors (like your retirement loan portfolio).
So who is obtaining these “subprime” auto loans? Usually this is a borrower who has a credit score below 600. Folks in this group are considered high credit risks.
Bank/Investors willing to take high risks
As Wall Street banks have found it tougher to profit under new regulatory regimes born out of the last subprime crisis, they’ve become more willing to underwrite riskier auto-loan asset-backed security sales. Investors, starved for returns with about $8 trillion of debt globally carrying negative yields, have in turn proven to be insatiable, further facilitating higher levels of risk in the market for the securities.
Losses increasing higher than expected
“Many companies are increasing their loan loss provisions, which has caused some formerly profitable companies to become unprofitable. Other newly formed companies are still striving to break even,” analysts at S&P including Amy Martin said in a March 20 report.
Is this similar to a pyramid scheme?
 The foundation for the loan (value of the vehicle) is a very poor investment, but initial investors may see a significant return on their investment, but as time passes those who buy this junk paper will find their investment lost because it never really existed.

Diane is a well respected Arizona bankruptcy and foreclosure attorney. As a retired law professor, she believes in offering everyone, not just her clients, advice about bankruptcy and Arizona foreclosure laws. Diane is also a mentor to hundreds of Arizona attorneys.
*Important Note from Diane: Everything on this web site is offered for educational purposes only and not intended to provide legal advice, nor create an attorney client relationship between you, me, or the author of any article. Information in this web site should not be used as a substitute for competent legal advice from an attorney familiar with your personal circumstances and licensed to practice law in your state. Make sure to check out their reviews.*



In Case You Missed It
Published On: September 13, 2026
Paying debt every month but getting nowhere can cost you years of income and thousands of dollars in interest. Before signing up with a debt management or debt settlement company, understand what debts are covered, what fees you may pay, whether creditors can still sue or garnish wages, and whether forgiven debt could create tax problems. For some people, bankruptcy may provide a faster, more complete fresh start and a chance to rebuild.
Published On: August 9, 2026
Debt-settlement companies promise to reduce what you owe, but creditors do not have to settle. Learn what federal regulators say about growing balances, lawsuits, fees, taxes and other debt-settlement risks before you stop paying your creditors.
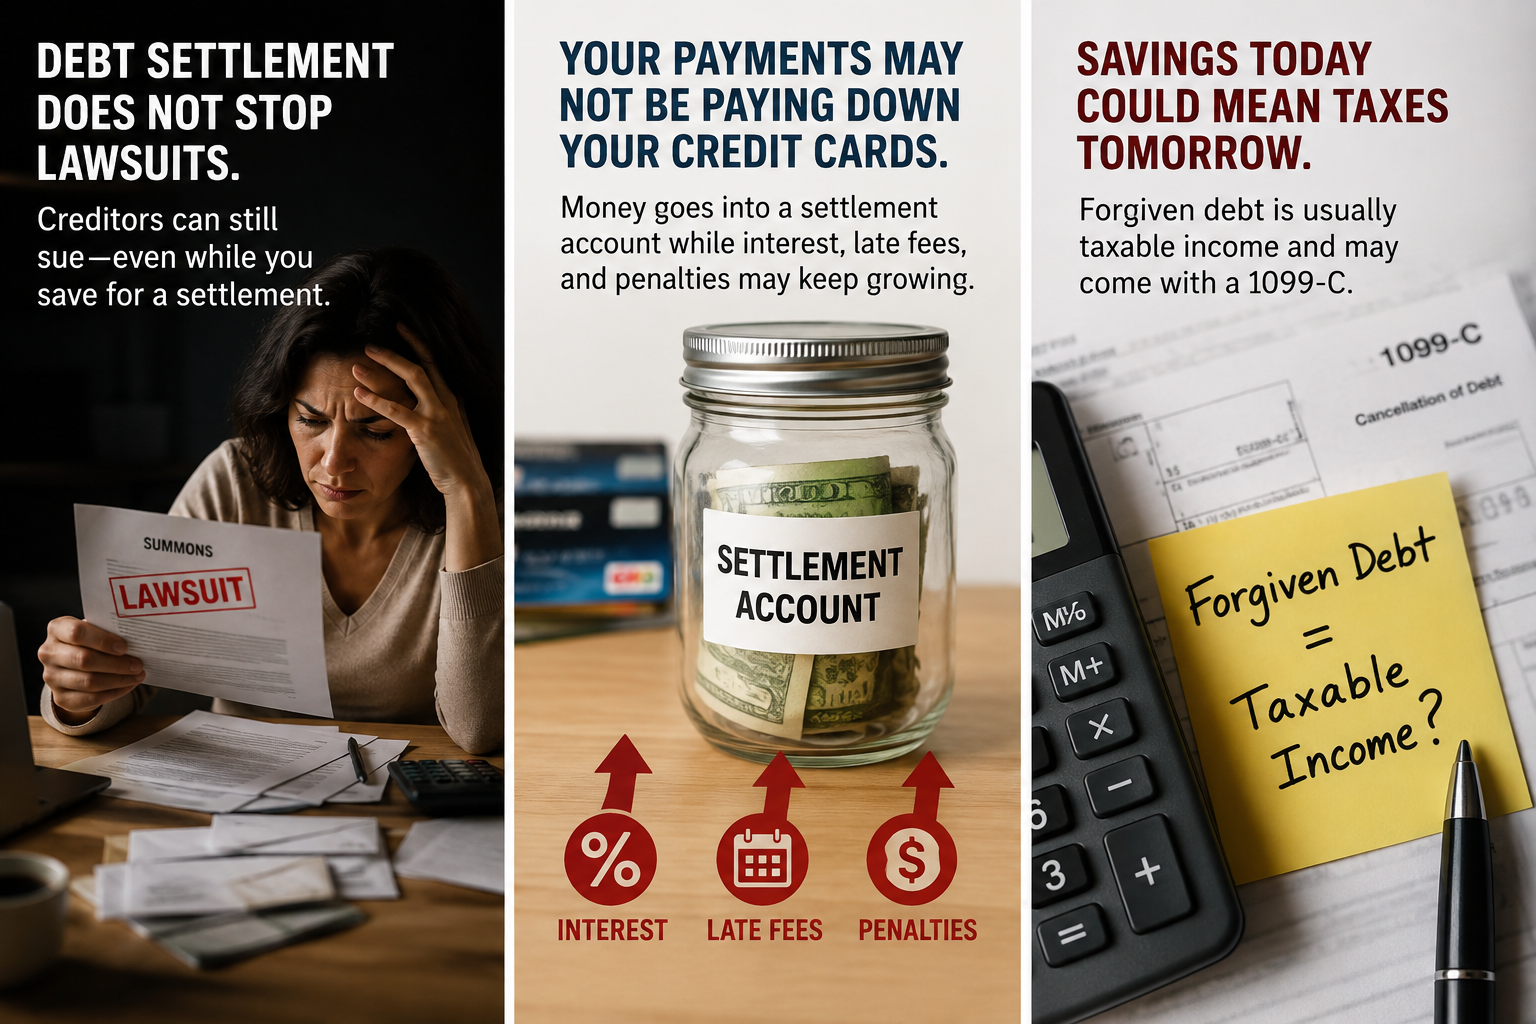
Published On: August 8, 2026
Debt settlement companies promise relief from overwhelming debt, but creditors do not have to settle and lawsuits can continue. Learn about the hidden fees, growing balances, tax consequences, and alternatives before signing a contract.
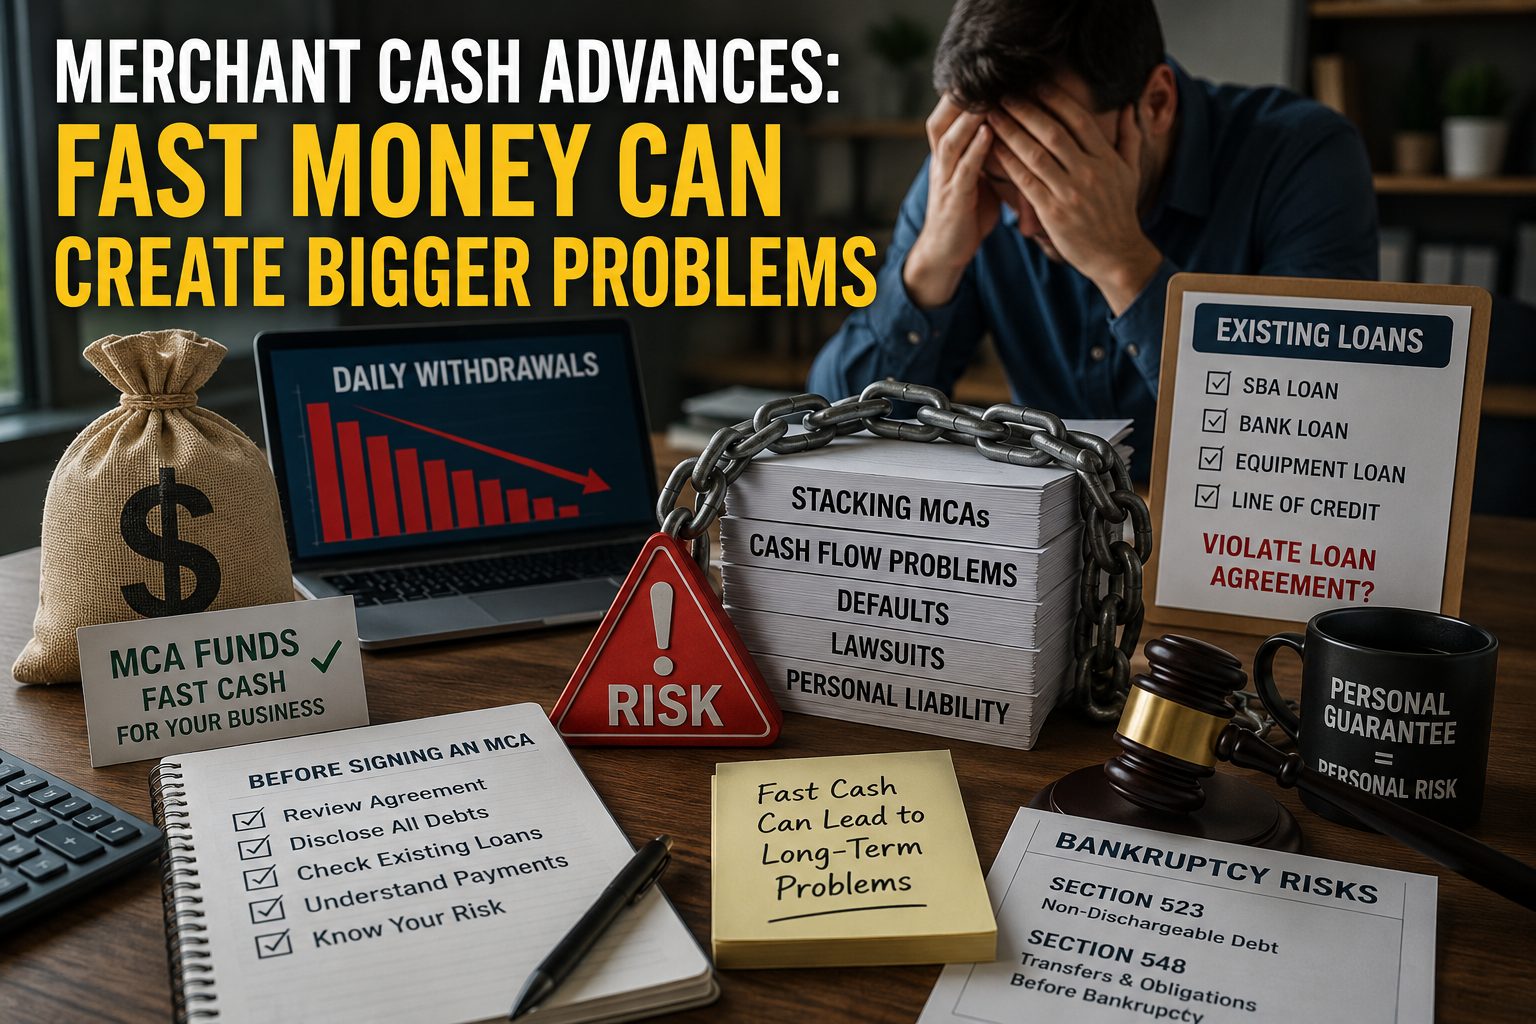
Published On: June 27, 2026
Merchant cash advances can provide fast cash, but daily withdrawals, stacked MCA loans, SBA loan conflicts, personal guarantees, and bankruptcy risks can quickly put a business and its owner in danger.